10 Year Hits 5% | Fed Hike Wednesday | Brent Back Above $100 | Positioning Turns Fragile
"The 10 year touched 5%, oil is back above $100 and the Fed is about to hike, and the S&P 500 is still less than 2% from its record. A market that should have cracked is not cracking, because the money that would force it lower is already short." — Proflex Panel
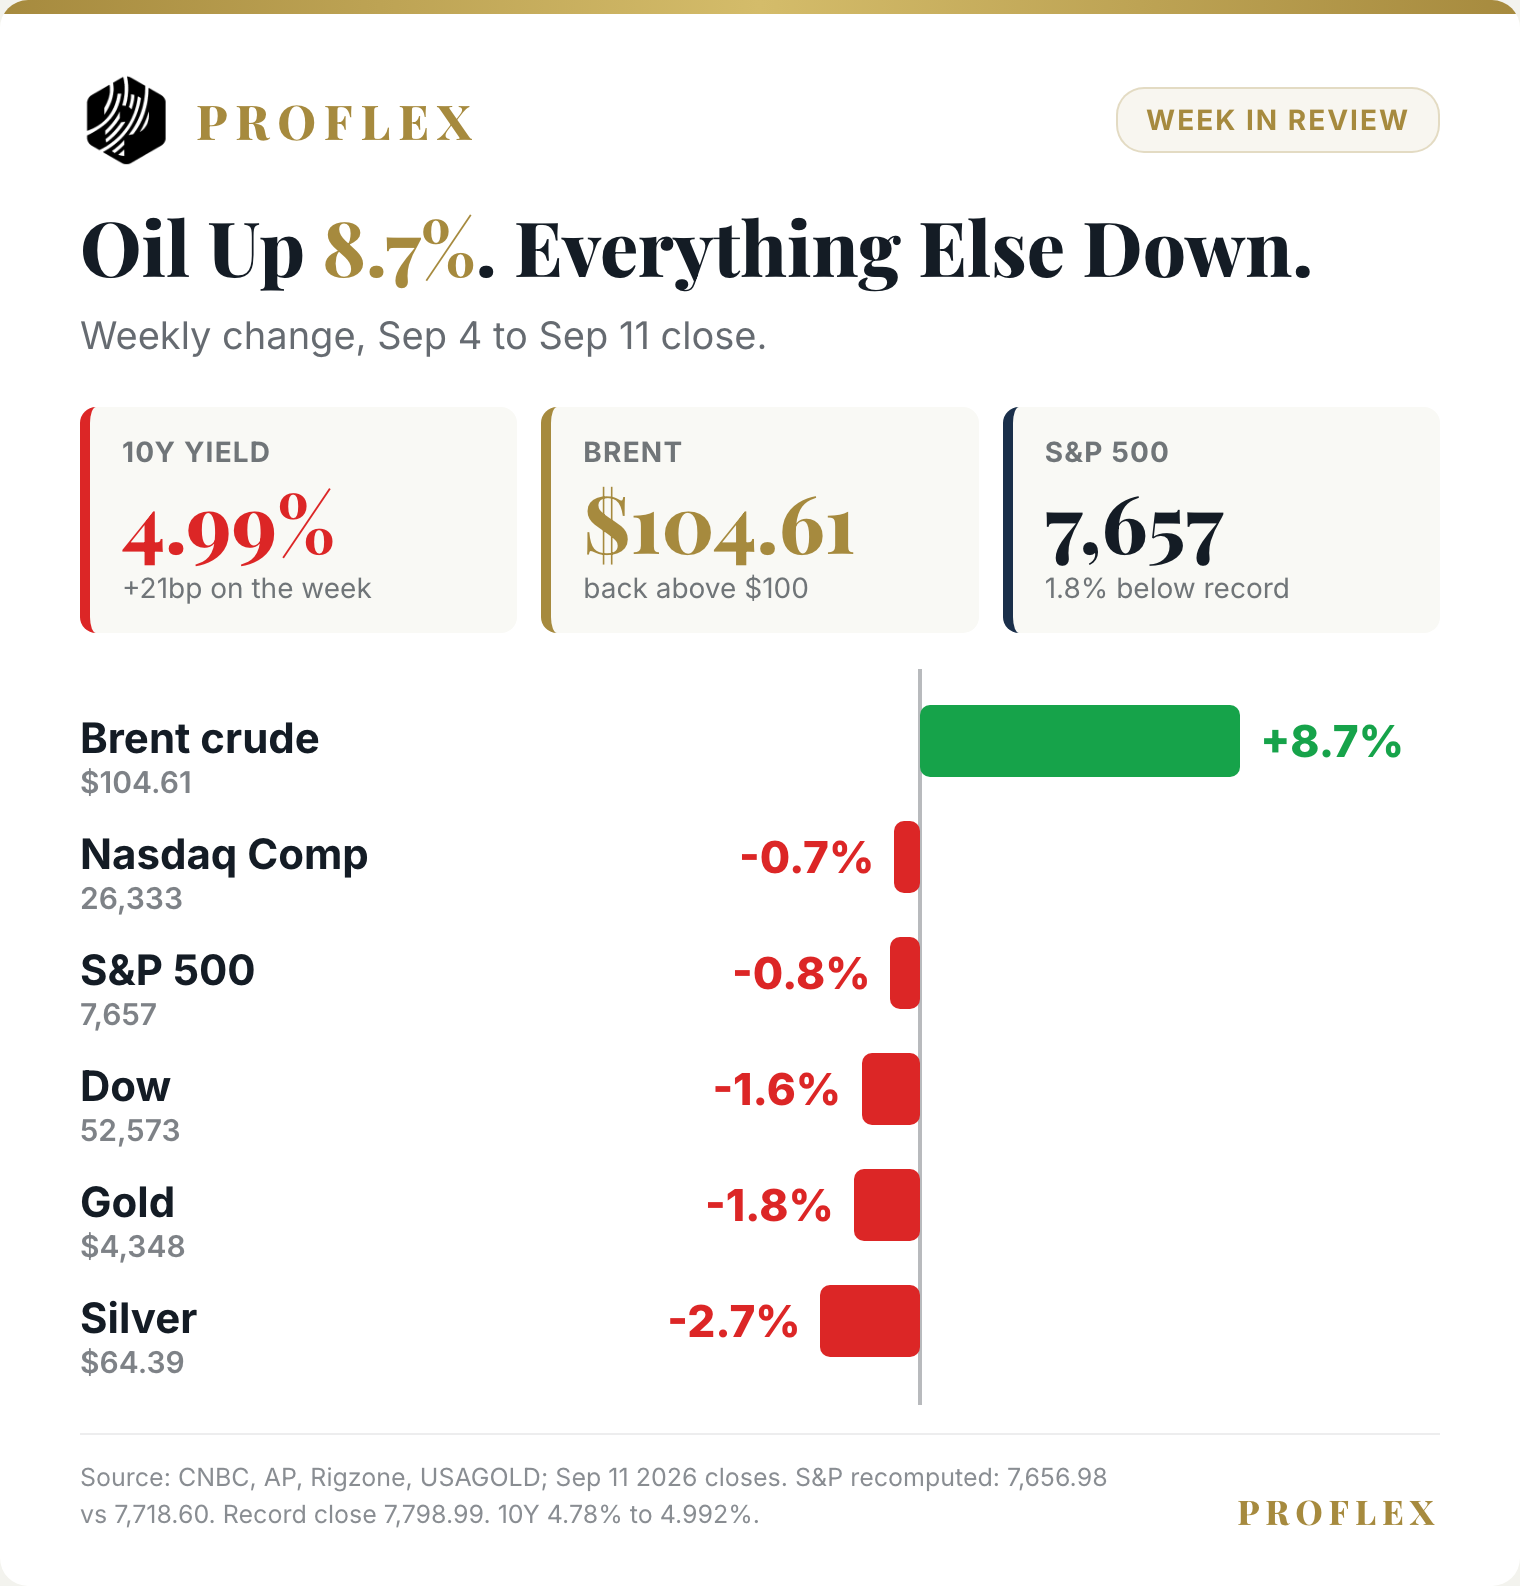
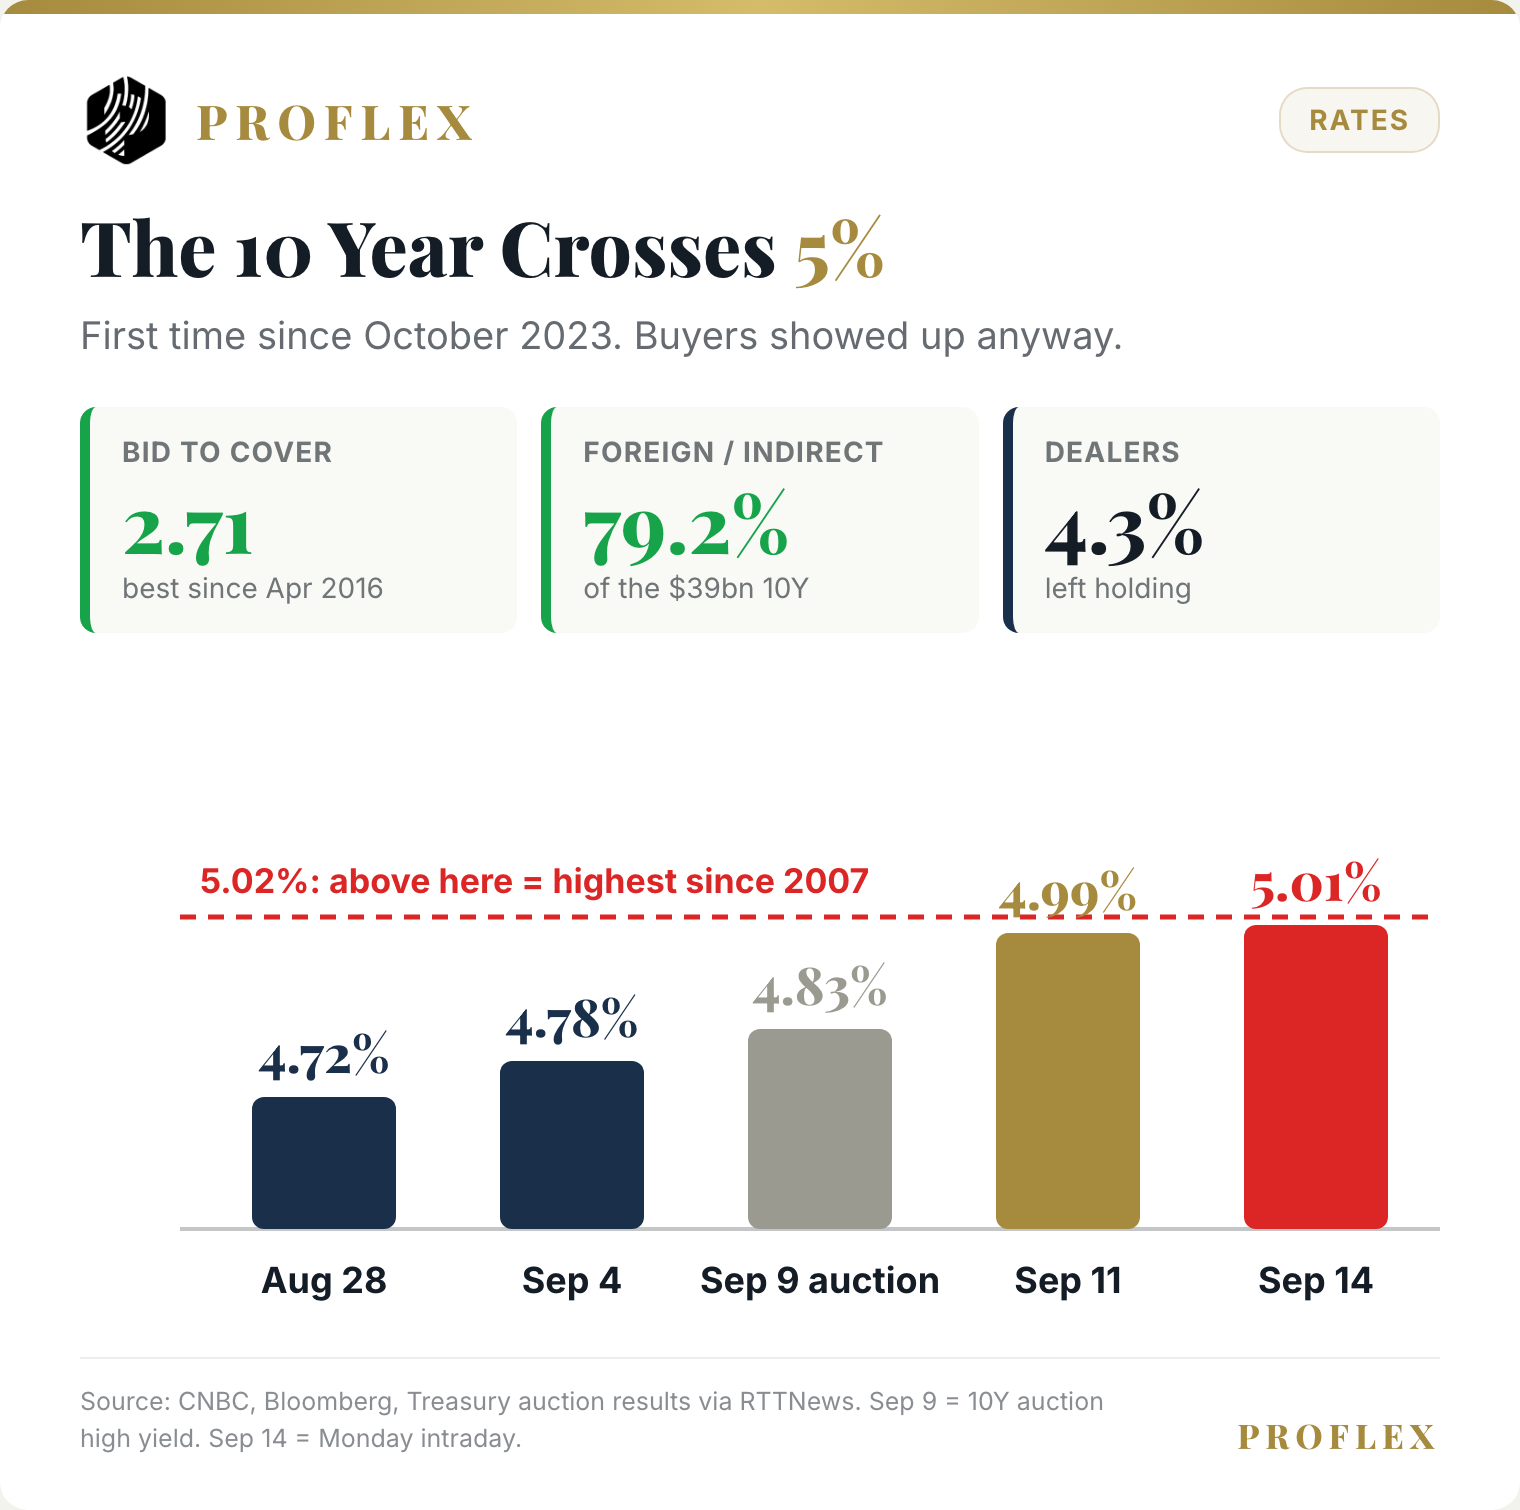
Every macro input moved against equities last week. Brent rose 8.7% to $104.61 after Saudi Arabia shut its East West pipeline following drone attacks. August CPI came in at 0.4%, with core at 0.3%, a tick hotter than expected. The 10 year closed Friday at 4.99% and on Monday morning traded at 5.01%, above 5% for the first time since October 2023. Futures now price roughly 86% odds of a hike on Wednesday.
And the S&P 500 finished the week at 7,656.98, down just 0.8% and about 1.8% below its record close of 7,798.99. Stocks fell four days in a row, then rallied 0.9% on Friday when oil and yields paused. BofA estimates the index came within about 50 basis points of the level where systematic funds would have started selling before that reversal pushed it clear.
This is the setup we described in April and May, when the war, yields and oil were all rising and the market went up anyway. The difference now is that valuations are high rather than low. The market is holding up anyway, and that tells you where the money is. The question this week is not whether the Fed hikes. It is whether oil or the 10 year breaks through the one level that would actually force a correction.
Insights from the Proflex Macro Call
The market is stuck, not broken. The S&P has been in a range just below its highs for more than a month. Underneath, the momentum trade has reversed. The rest of the market has caught up while semiconductors are still well below their May and June highs. Every dip on yields or debt worries has been bought, and Friday’s expiry turned into a short covering rally.
There is no fuel for a crash. As Raman put it, a bubble needs leverage to burst, and right now the leverage is on the short side. Hedge funds and leveraged traders are net short, while fundamental investors are still long the AI story. "In an ideal world, when yields are touching 5%, the market should have crashed by now already. That is not happening."
Two triggers, and only two. Brent back to its prior highs of $120 or more, or the 10 year holding above 5%. Without either one, expect a sideways market where the Magnificent 7 take turns: when one corrects, another rallies and the index stays put.
Bitcoin looks better than gold. Bitcoin is consolidating in a tight $77,000 to $81,000 band above a 200 day average that has turned up sharply, and it held support on a five year weekly trend line. Gold and silver are both still below their 200 day averages and in wait and watch mode, with this weekend’s BRICS summit as a possible catalyst for gold.
AI capacity does not go to waste. Even if AI is being overbuilt for today’s use cases, new uses always arrive for the capacity. The bigger story is energy. After two decades of flat US power generation, the buildout is putting the US on a China like path, and no country in the last century has added that much generation without growth following. Our full report on AI ROI lands next week.
Last week we said the enlarged Treasury buybacks would not be enough on their own, and that the 30 year, not the S&P, was the place to watch. The 30 year went from 5.24% to about 5.36%, and the 10 year followed it through 5%. A move above 5.02% would be the highest level since July 2007.
What the headlines missed is the auction. Wednesday’s $39 billion 10 year sale cleared at 4.834% with a bid to cover of 2.71, the highest since April 2016. Indirect bidders, the category that includes foreign central banks, took 79.2%. Primary dealers, who absorb whatever nobody else wants, were left with just 4.3%. A market that is running away from Treasuries does not produce that result.
Proflex View: A 5% risk free return for ten years is attractive to every fund that just wants to park dollars, and the auction proves the demand is there at these levels. With a hike this week, the Treasury can keep funding at the short end and using the proceeds to buy back the long end. Japan has run that playbook for decades. We do not see 5% as a catastrophe. We see it as a trigger only if it holds and keeps climbing.
CPI Locked In The Hike. Wednesday Is About The Next One
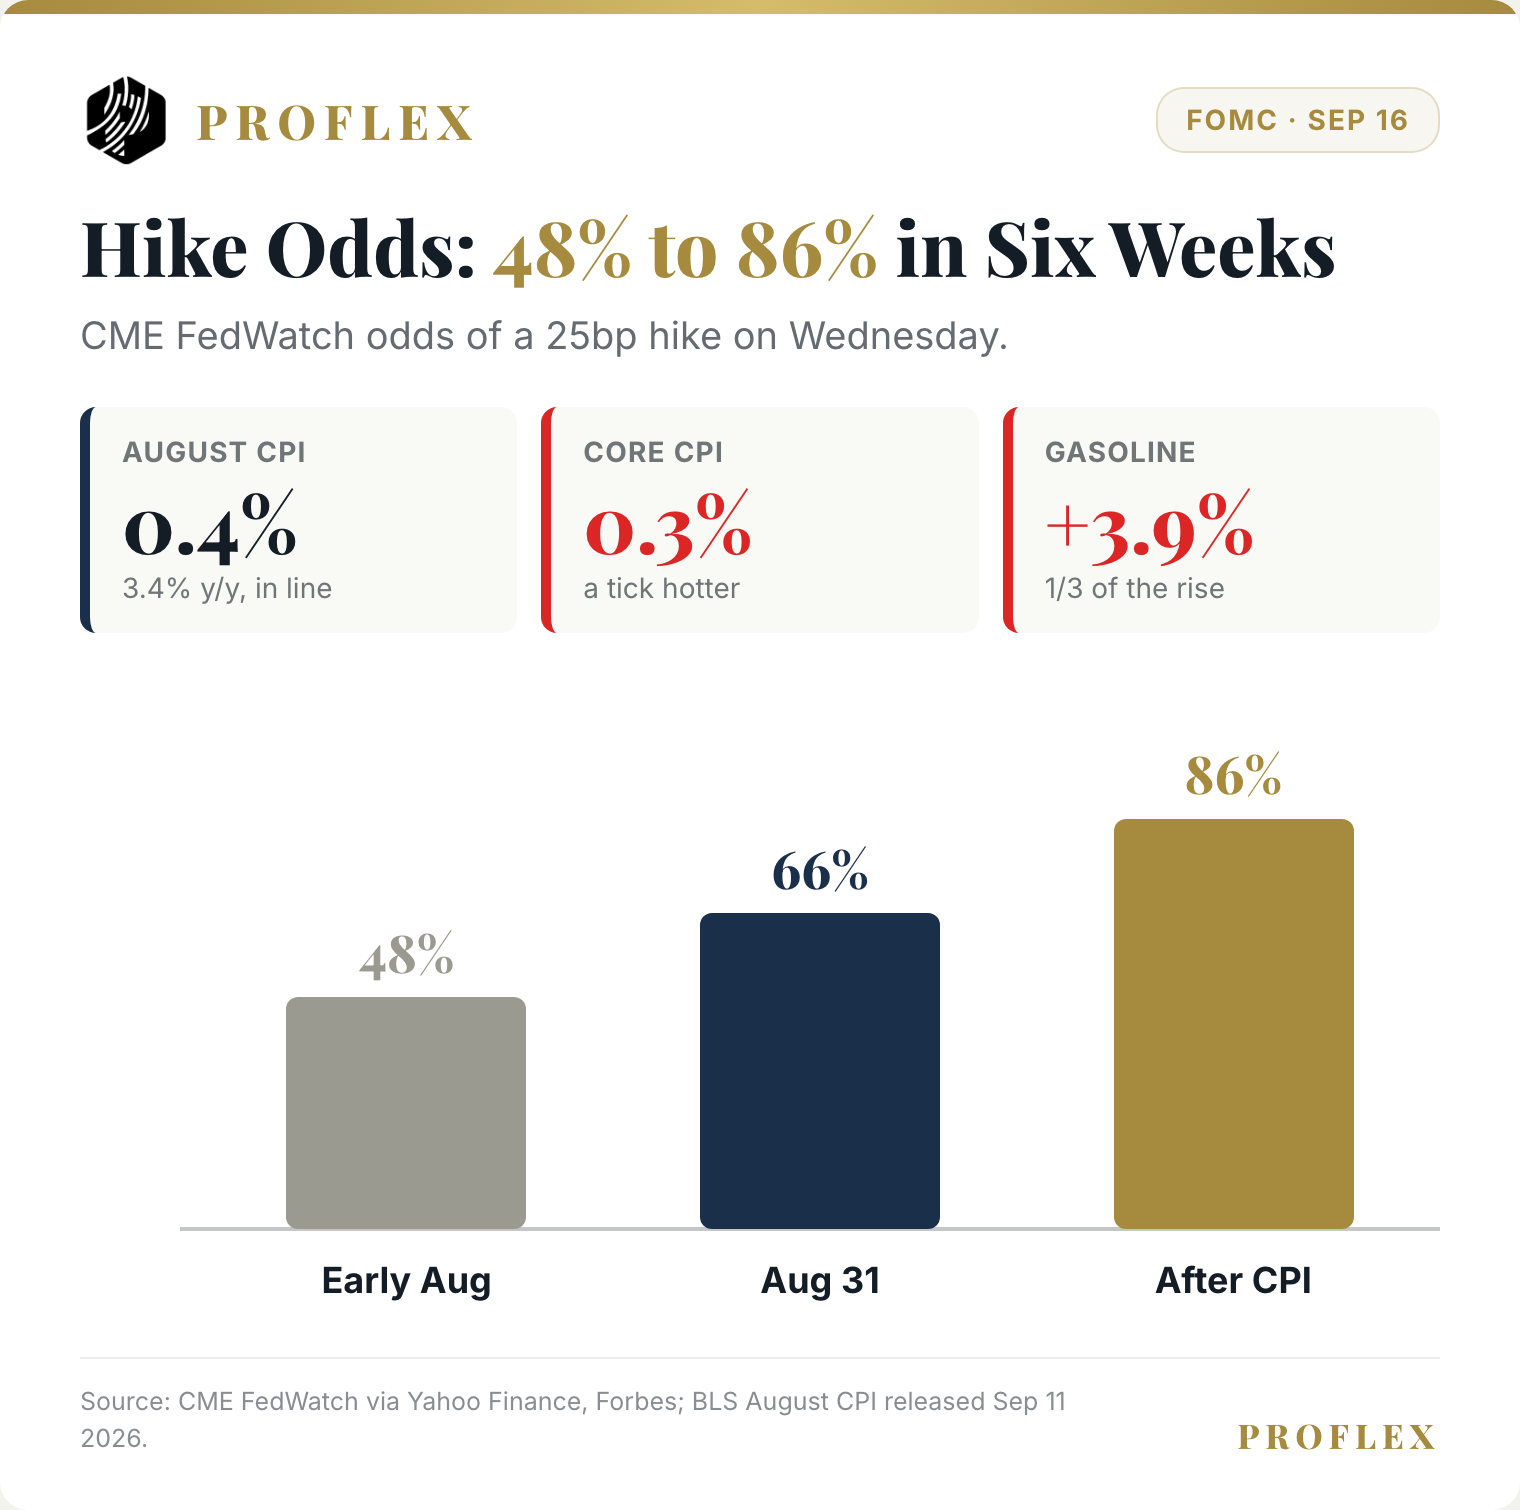
Our call last week was that a 0.4% headline with a soft core would lock in the hike and the market would take it in stride. We got the headline right, and it was in line at 0.4% and 3.4% year over year. We got core wrong. It printed 0.3%, not 0.2%. Gasoline rose 3.9% and made up over a third of the monthly increase, and shelter picked up to 0.3% after two months at 0.1%.
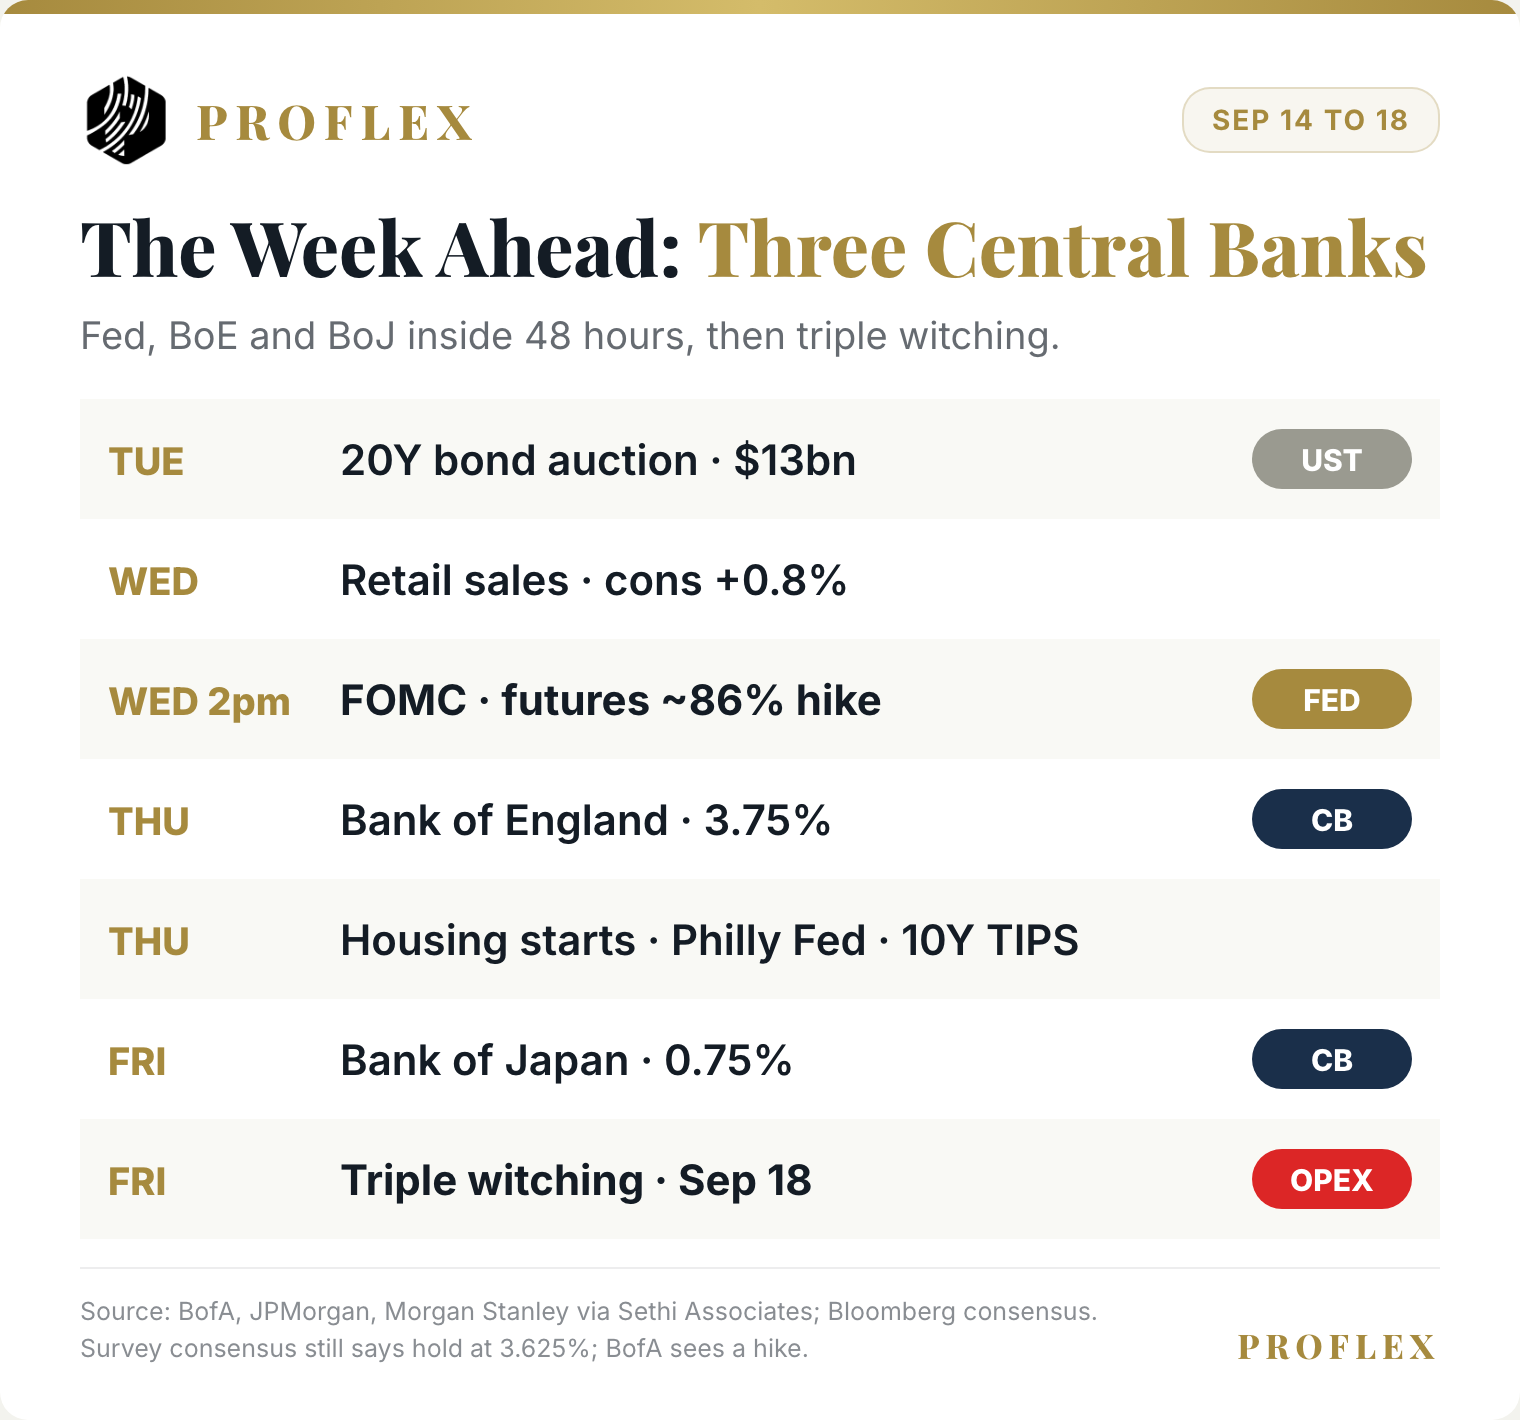
Hike odds moved from 48.4% in early August to 65.9% on August 31 and roughly 86% after the print, per CME FedWatch. Money markets have also started to price a second hike later this year. The survey consensus still says hold at 3.625%, as does Morgan Stanley, while BofA looks for 25 basis points to a 3.875% midpoint. Wednesday brings new projections as well, so the dot plot matters more than the decision itself. The Bank of England follows Thursday and the Bank of Japan decides overnight into Friday.
Proflex View: A 25 basis point hike is priced and is not the risk. The risk is the dots showing more than one. A hike driven by energy with core near 0.3% is a Fed protecting its 2% credibility, not chasing a runaway economy. If Warsh frames it that way, the long end can actually calm down after the decision.
Brent Back Above $100, And The War Is Not Ending
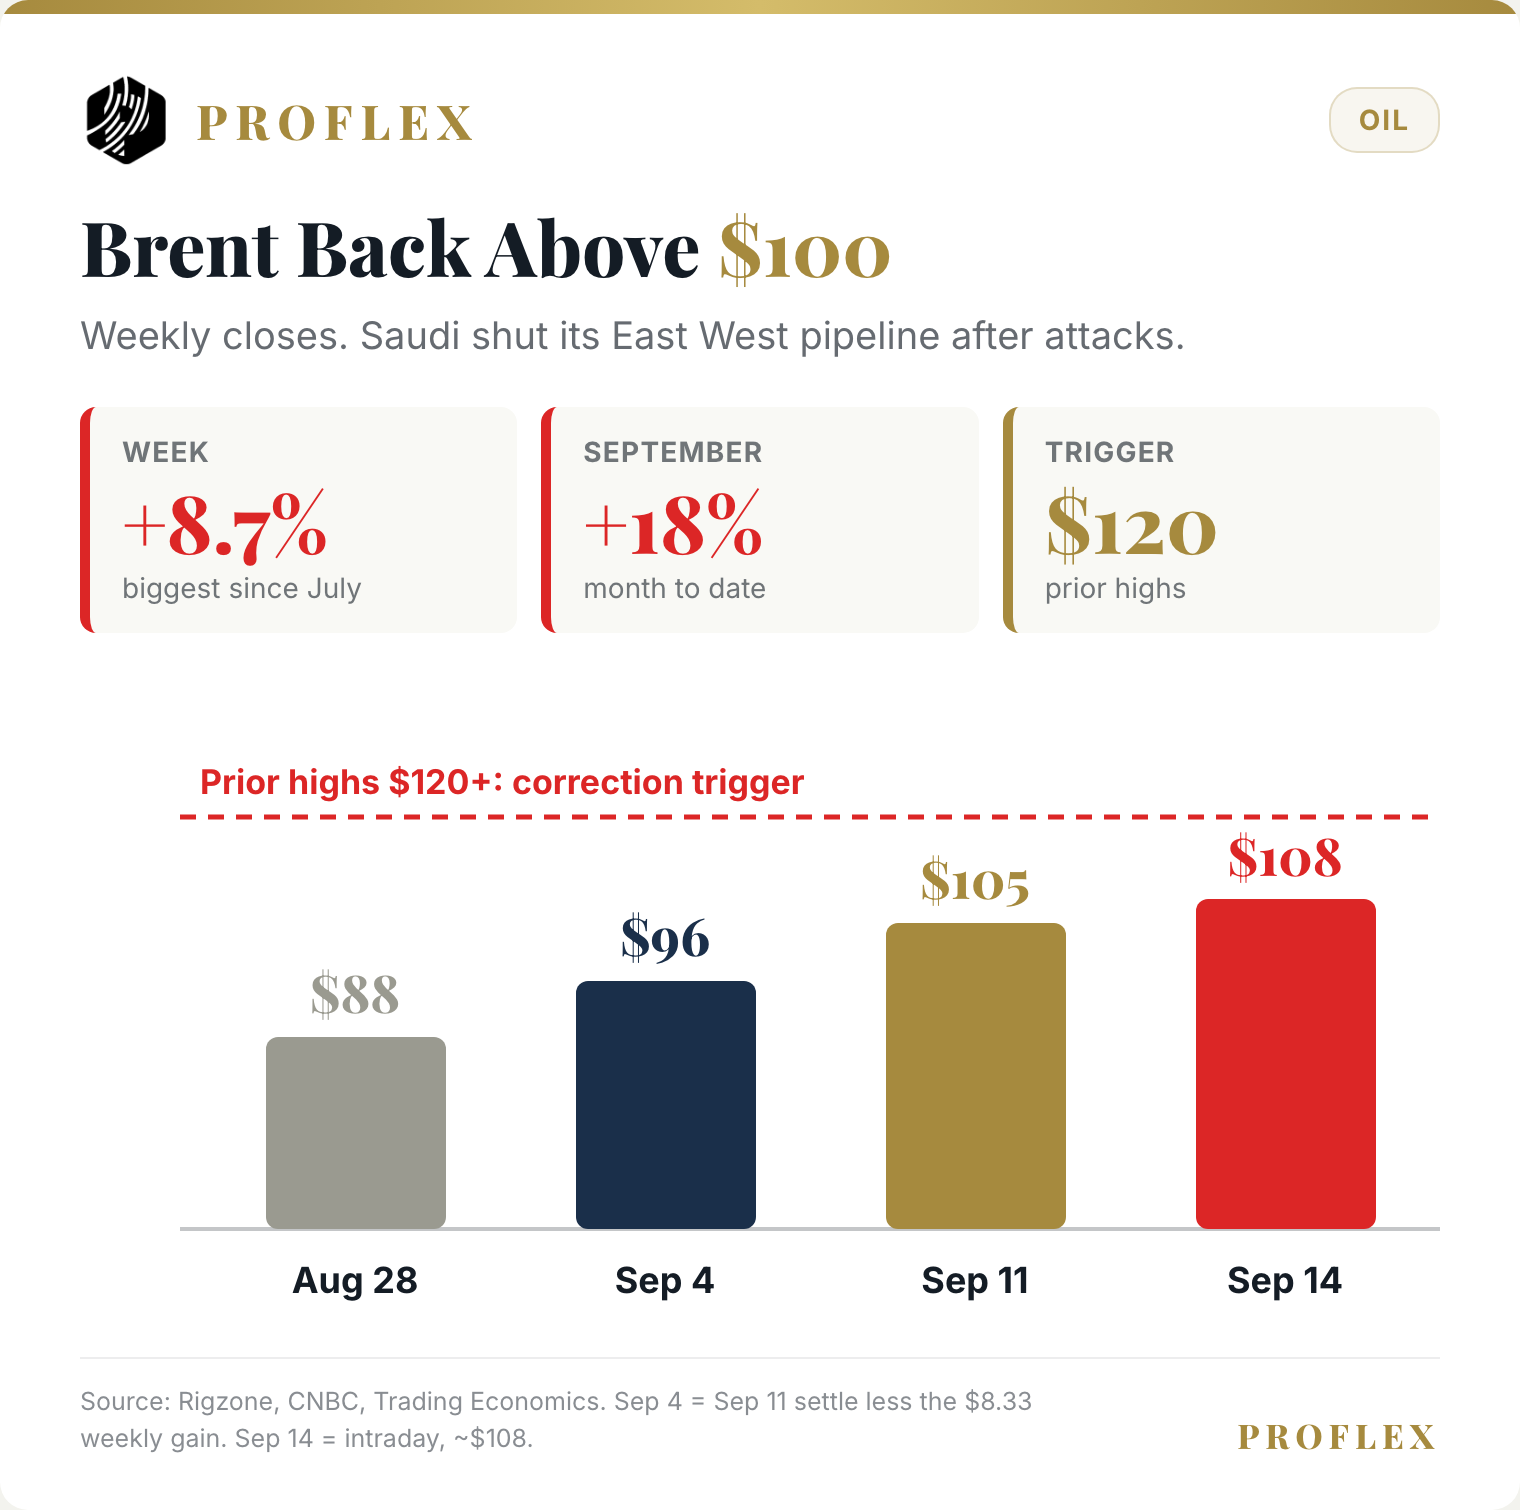
Brent settled Friday at $104.61, up $8.33 on the week, and traded toward $108 on Monday, a four month high. WTI closed at $102.48 on Thursday, its highest settle since May 19. Oil is up more than 18% in September. The trigger was Saudi Arabia shutting its East West pipeline, which had been carrying about 7 million barrels per day to the Red Sea as the workaround for blocked Gulf exports. That came after US forces destroyed five Iranian tankers. The White House has now discussed the possibility that the war runs past January 2029.
Raman’s read on the call was blunt. This was always an asymmetric war in which Iran’s only real weapon is economic damage, and the November midterms give it every reason to keep inflicting that damage. He does not expect a settlement before November.
Proflex View:For four weeks we have marked the oil call against ourselves, and Brent above $100 settles it: the Iran risk was not priced. What matters now is the ceiling. Every prior route closure has been a short term shock that the market eventually traded back down, including the round trip from the highs to $72. Below $120 this is inflation pressure the market can absorb. A return to $120 or more is the single clearest trigger for a real correction.
AI: Oracle Cleared The Bar We Set
Last week we called Oracle the better read on AI, because backlog turning into revenue shows whether customers can actually pay. It delivered. Revenue was $19.35 billion against $19.14 billion expected, up 30%. Cloud infrastructure revenue rose 121% to $7.4 billion, and adjusted EPS was $1.92 against $1.74. Management raised fiscal 2027 to at least $90 billion. The stock, down 5.4% during the session, gained about 4% after hours.
Proflex View: Taken together, Broadcom and Oracle show AI demand is real at both the chip and capacity layers. Near term the AI trade stays fragile, because valuations assume growth and the market sells any hint of a slowdown. Over the longer run, the only real competition to the US buildout is China, and the West will still run on US AI.
Technicals & Institutional Flows
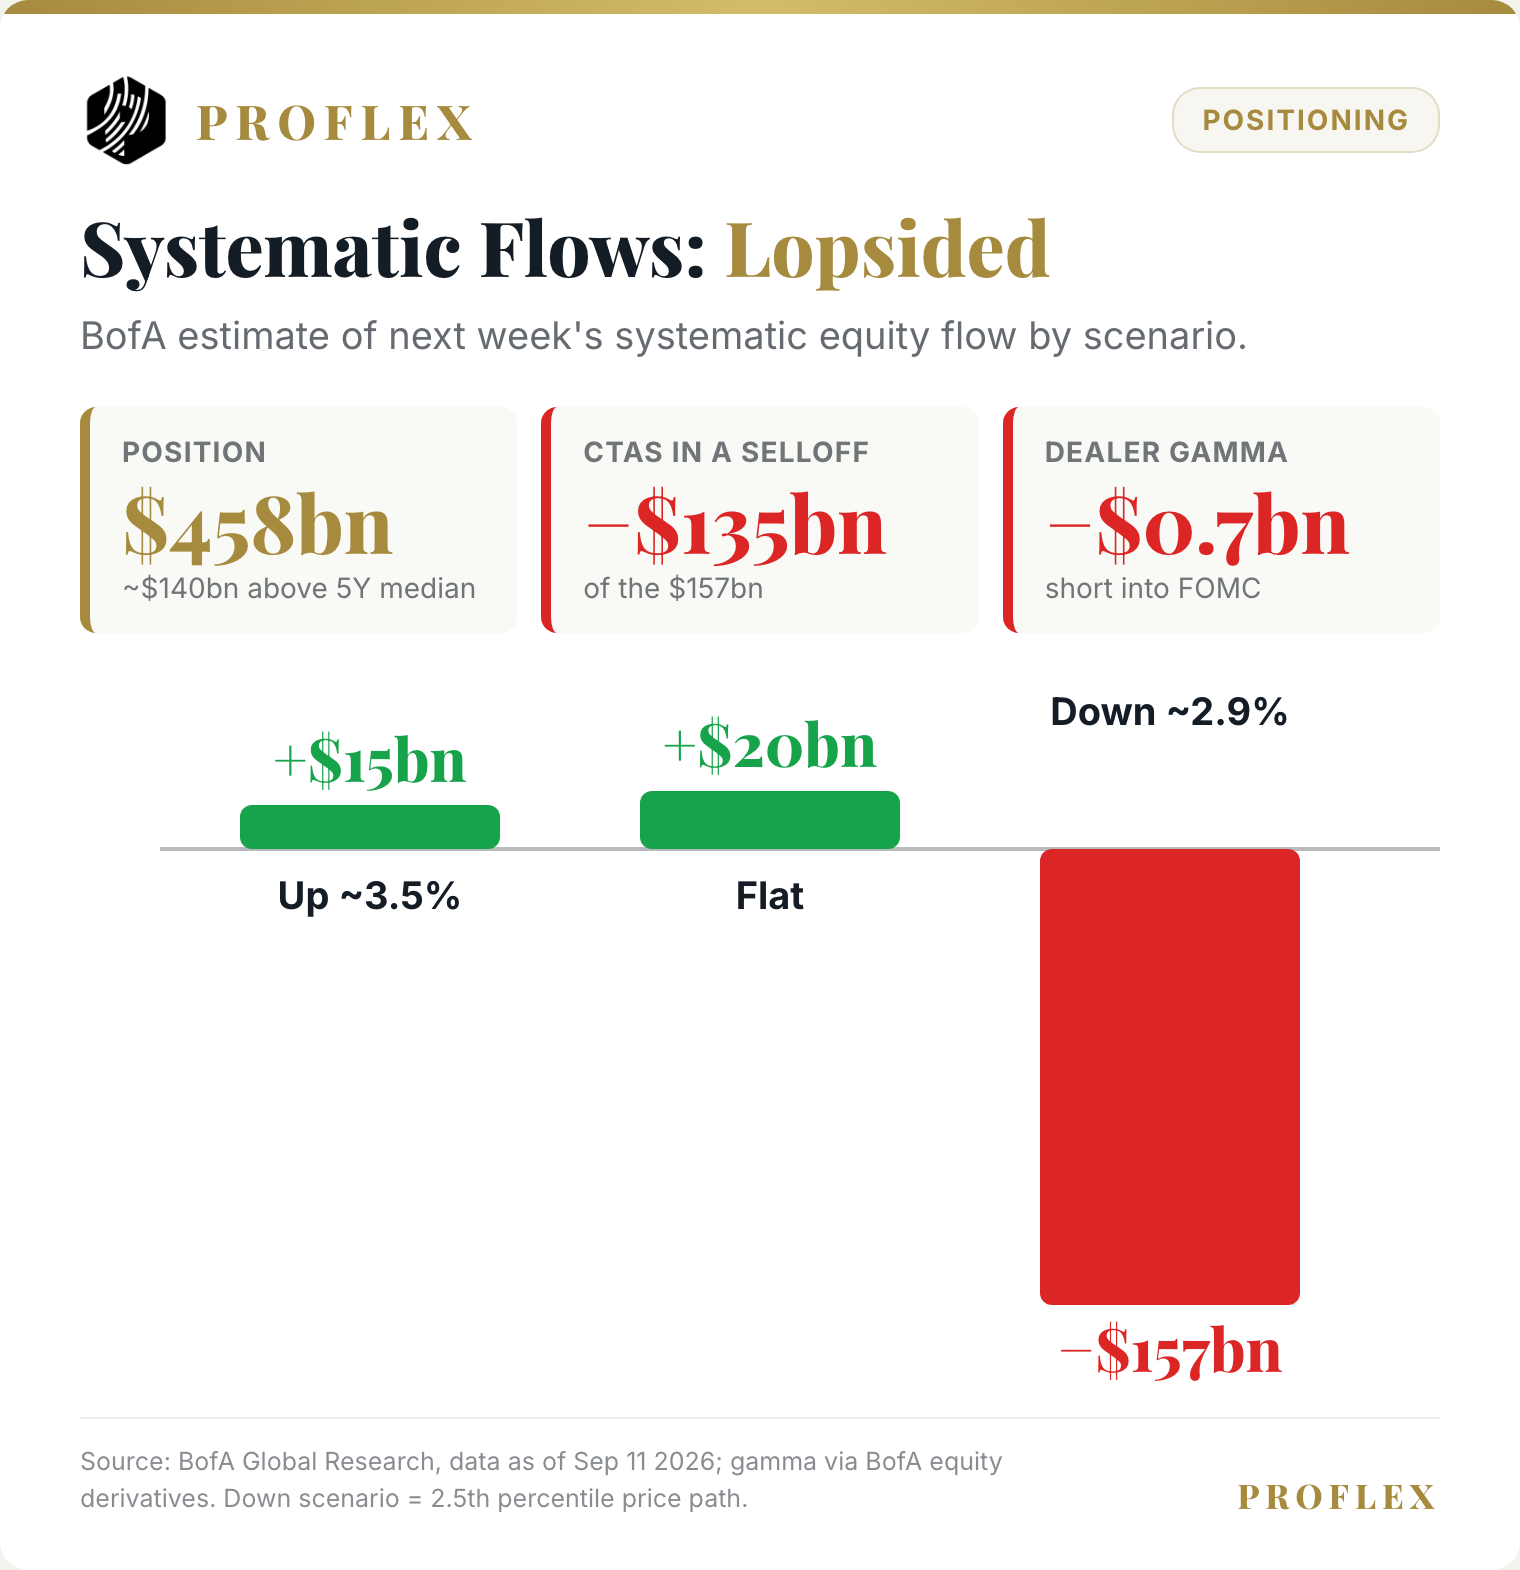
Gamma. Heading into the FOMC, BofA estimates hedgers are net short gamma across expiries by about $0.7 billion. That makes dealer hedging a destabilizing force: market makers buy as prices rise and sell as they fall. Within the September monthly, hedgers are net short about 25,000 contracts between 7,500 and 7,650 and net long about 18,000 between 7,650 and 7,800. That position can push gamma more negative on a downtick and more positive if spot rallies, so a move lower could build quickly.
CTAs and systematic funds. BofA puts systematic global equity positioning at about $458 billion. That is down from last week’s high but still roughly $140 billion above its five year median of about $318 billion. Faster trend signals have rolled over, and sell triggers now sit close: about 0.4% lower for the Russell and 1.4% for the S&P. Next week’s flow estimates by scenario:
Flat market: +$20 billion of buying (from +$35 billion the prior week)
Up market (~+3.5%): +$15 billion of buying (from +$5 billion)
Down market (~−2.9%): −$157 billion of selling, with CTAs about $135 billion of it (from −$126 billion last week and −$163 billion the week before)
Expiry. Friday is the September triple witching, the quarterly expiry Raman flagged on the call as now topping $6 trillion, about double its size a year ago.
Proflex View: Systematic funds would buy modestly in a flat or rising market and sell heavily in a falling one. With dealers short gamma into Wednesday, a hawkish surprise would likely produce a bigger move than the news alone justifies. Friday’s expiry then resets that positioning.
🔍 What We’re Watching
The 20 year auction Tuesday: does the 10 year’s strong demand hold further out the curve?
FOMC at 2pm Wednesday: the dot plot and whether it signals a second hike
Brent against $120, the correction trigger
The 10 year against 5.02%, the highest since 2007
Triple witching Friday, with the S&P sell trigger about 1.4% below Friday’s level
Bitcoin holding the $77,000 to $81,000 band, and gold after the BRICS summit
🧭 Proflex Playbook – Watch the Triggers, Not the Headlines The macro is about as bad as it has been all year and the index is still within 2% of its record. We are watching two levels, Brent at $120 and the 10 year holding above 5%. Until one of them breaks, this is a rotation market, not a crash market. Our conviction stays anchored in the data:
Focus on Structural Growth: Continue to overweight the secular AI theme, recognizing its multi-year runway.
Anticipate Shallow Corrections: Use dips as accumulation opportunities, not reasons for fear, understanding that "none of the corrections stick."
Diversify Thoughtfully: Recognize the "decorrelation" across asset classes; consider gold, silver and Bitcoin for portfolio resilience.
Develop Mental Models: Prioritize long-term planning (6-12 months out) over short-term news, aiming for consistent, incremental gains.
If you're an All-Access or Managed Portfolio subscriber, our positioning has already shifted ahead of this moment—scaling up asymmetric hard asset plays while hedging for earnings volatility and geopolitical tail risks.
Proflex All-Access: Your Market Compass
Explore the financial markets with Proflex All-Access, your comprehensive resource for deeper market understanding and active participation. This premium service offers subscribers exclusive insights and actionable investment advice, giving you a significant edge in various market conditions.
Proflex All-Access provides detailed analyses and recommendations to optimize your investment strategy. Our specialized newsletters include:
• Growth Gazette (Contains Crypto Pulse) : Aimed at achieving above-market returns for aggressive portfolio growth.
• Income Insider: Focused on conservative strategies and income generation for yield-seeking investors.
Until next week, — The Proflex Team Trusted Macro Insights. Calm Investing. Tactical Trades.
Elevate your financial IQ
ProFlex® by Blockstart Research Legal Disclosures
ProFlex® by Blockstart Research, the premium newsletter product series, provides informational and educational content only and does not offer personalized investment advice or establish a fiduciary relationship. While we rely on reliable sources and research, the information is not tailored to individual financial situations. Readers are urged to consult qualified financial professionals before making investment decisions. We do not guarantee the accuracy, completeness, or timeliness of the information and are not responsible for any investment decisions based on this newsletter. Investing carries risks, and past performance doesn't predict future results. By accessing this newsletter, you acknowledge that we are not liable for actions or decisions resulting from its content. Please conduct due diligence and seek professional advice as needed.
Proflex Institutional Research Series
Elevate Your Investment Game!
ProFlex® is designed to optimize your time, ignite your investment IQ, and maximize your financial potential.